

Jersey Funds and Regulatory Industry Update – September 2026
Update
Update
Speakers from our team shared a practical overview of the key developments shaping Jersey’s funds industry, including COBO reform, recent Companies Law amendments, the evolving EU and UK AIFMD regimes, and Jersey’s broader regulatory outlook.
COBO update (Stefan Chinniah)
Overview
The repeal of the Control of Borrowing (Jersey) Law 1947 and its associated Order (together COBO) is an early measure under Jersey’s competitiveness programme, aimed at reducing cost, duplication and administrative burden for the financial services industry and local businesses.
COBO has long served as a regulatory gateway, so its repeal is not a straightforward process and requires coordinated amendments to existing laws and the introduction of a modern framework for products that will remain subject to JFSC approval or registration.
Phase one: initial reforms
- The first phase took effect on 13 April 2026 and brought about some immediate changes.
- Prospectuses for non-Jersey funds may now be circulated in Jersey without COBO consent, unless the offer is made to retail investors. Separate fund services business considerations may still apply to associated distribution activity.
- Non-fund Jersey unit trusts, including Jersey property unit trusts, no longer require a COBO consent and can now be established very quickly.
- COBO requirements have also been removed where certain regulatory exemptions apply, making it easier for Jersey vehicles to provide investment business or trust company business services to a wider range of structures and for Jersey service providers to act for certain non-Jersey vehicles.
Phase two: repeal and replacement framework
- Phase two is the larger project and is intended to repeal COBO in full. Entity formation and registration requirements would instead sit directly in the relevant companies, partnerships and other entity laws.
- A proposed Financial Products and Prospectuses Law would preserve an appropriate JFSC gateway for products such as Jersey private funds and digital asset issuers. The relevant fund services business or trust company business provider would register the vehicle.
- Existing products holding COBO consents are expected to be deemed registered under the new regime, avoiding a wholesale re-registration exercise. A separate overseas prospectuses order would retain the phase one approach of focusing principally on retail offers, while existing continuance requirements would be maintained.
- Further work is required, including scrutiny, debate by the States Assembly plus the Privy Council approval process, together with extensive updates to subordinate legislation and JFSC codes, policies, guidance and systems. Implementation is currently targeted for the end of 2027.
Recent Companies Law amendments (Felicia de Laat)
Felicia took a practical look at the recent update to the Companies Law, focusing on the top ten changes most likely to make a real difference for directors and administrators:
1. The new administration regime
Jersey’s new administration regime introduces a formal corporate rescue process for companies in financial difficulty. It gives directors an additional restructuring tool, aimed at preserving value and improving creditor outcomes where a viable business may otherwise face winding up.
2. Greater flexibility for capital contribution
The amendments allow cash or assets to be contributed to a Jersey company without issuing new shares, creating greater structuring flexibility and helping avoid unnecessary changes to ownership percentages. This brings Jersey closer to jurisdictions such as Luxembourg and reflects a broader move towards a more flexible company law framework.
3. Correcting mistakes in the register of members
Directors may now, where appropriate, correct manifest errors in the register of members without applying to court. This should reduce time, cost and administrative burden where obvious mistakes need to be fixed.
4. Simplified share buybacks and redemptions
The amendments simplify certain share buyback and redemption processes, including allowing nil or partly paid shares to be redeemed or purchased. This should make routine corporate transactions more efficient and reduce unnecessary process and paperwork.
5. Simplified ratification of defective distributions
Directors can now remedy certain defective distributions without a court application, where appropriate. This should reduce unnecessary cost and delay where the company remains solvent, and no one has been prejudiced.
6. Share certificates become optional
Companies can now dispense with share certificates, where appropriate, reducing paperwork and aligning the law with modern electronic record keeping. This should make company administration simpler and avoid unnecessary practical difficulties where historic certificates are missing or hard to locate.
7. Abolition of the 30-shareholder rule
Private companies will no longer lose their status simply because they have more than 30 shareholders. This gives greater flexibility for investment structures, employee ownership arrangements and other companies with larger shareholder bases.
8. Direct voting by shareholders
Shareholders can now vote directly without needing to appoint a proxy. This should make meetings easier to run, support shareholder participation and align governance processes with modern expectations.
9. Digital governance reforms
Voting is now expressly allowed by telephone, electronic and other communications technology. This makes participation easier, faster and more accessible for directors, administrators and shareholders across different jurisdictions.
10. Simplified written shareholder resolutions
The written shareholder resolution process has been modernised, with non-unanimous resolutions becoming the default unless the articles say otherwise. This should make private company governance faster, simpler and more reflective of how shareholder decisions are made in practice.
AIFMD update (Ben Marshall)
Current status
- The EU and UK AIFMD regimes continue to diverge with the EU pursuing further regulation while the UK looks to simplify and consolidate its regime. AIFMD II has applied in the EU since 16 April 2026, while the UK replacement regime is not expected until 2028.
- Managers active in both markets should start planning for separate EU and UK compliance requirements.
Non-EU AIFMs
- For non-EU AIFMs, the main impact is expected to be more reporting and disclosure, rather than changes to fund structures. Managers should prepare for more detail in Annex IV reporting and investor disclosures, with a new Annex IV template expected in 2027.
- NPPR access remains available across the EU, but managers should check the relevant entry conditions carefully.
- Jersey structures should remain attractive, with increased reporting likely to be the main practical impact.
EU AIFMs
- EU managers will need to pay particular attention to credit and open-ended fund strategies. Loan-originating AIFs will be subject to new rules on policies, concentration, risk retention, leverage and open-ended structures.
- Open-ended EU AIFs will need to choose and support at least two liquidity management tools.
- Delegation to Jersey remains available, although EU AIFMs will need to meet enhanced rules on appropriate oversight of delegates.
UK AIFMD proposals
- The UK is expected to introduce a lighter and more flexible regime. Proposals include a NAV-based tiering system, simpler leverage rules, streamlined delegation and simplified reporting.
- The UK NPPR regime will remain, although a public register of funds using this route is proposed.
- Jersey is expected to introduce a UK-focused AIF Code once the UK position is settled.
- Clients who want to respond to the FCA consultation should do so before the October 2026 deadline.
Jersey implications
- Jersey implemented AIFMD II in full in anticipation of a third country passport becoming available. As this now appears increasingly unlikely, and the UK proposes to adopt a different approach, Jersey may need to consider whether full alignment with both regimes delivers sufficient benefit.
- Despite the divergence in the EU and UK regimes, Jersey remains an attractive option for managers seeking access to both markets.
- Those operating in Jersey will, however, need to monitor developments across the two regimes and prepare for greater complexity in reporting obligations.
Jersey’s regulatory outlook (Mike Jones and Tom Grogan)
Competitiveness programme
- Jersey’s wider competitiveness programme remains a key priority for the Government and the financial services industry.
- Since our January update, the Government has published its ‘Time to Win’ action plan. Upcoming workstreams include improving the efficiency of eKYC process, amending the guidelines and scope in relation to Schedule 2 of the Proceeds of Crime (Jersey) Law 1999, a potential new funds product for high net worth or sophisticated retail investors, and reviewing the intermeddling regime.
Digital assets
- Jersey is assessing where it can establish a genuine competitive advantage in the digital assets market.
- The preferred focus is on institutional and tokenised assets, drawing on Jersey’s existing strengths in private equity, corporate structuring and commercial real estate as these sectors adopt tokenisation and digital payment flows.
- Jersey’s legal and regulatory framework is considered broadly suitable for institutional digital asset activity. The COBO reforms should further strengthen its position, although targeted legislative amendments or additional regulatory guidance may still be required.
JFSC update
- Supervision: the JFSC is moving towards a more agile, data driven and risk focused approach, including shorter, targeted examinations and revised gradings of findings.
- Bank licensing: following the simplification and modernisation of JFSC’s bank licensing policy, there is growing interest from both new banks looking to move to Jersey and existing regulated businesses that may now be eligible to apply for a banking licence under the revised policy.
- Civil penalties: the final revised methodology and guidance have been published.
- Deferred prosecution agreements (DPA): entering into a DPA with the Attorney General will not necessarily prevent separate JFSC enforcement action according to some recent guidance issued by the JFSC.
- Outsourcing: recent thematic findings indicate generally strong compliance, but the JFSC remains focused on whether firms have credible contingency plans if a group, technology or other outsourced provider becomes unavailable.
- Financial crime: continuing areas of focus include remediation, monitoring, due diligence and regulatory reporting.
- Simplification programme: the JFSC has amended or withdrawn a number of guidance notes. Firms should review the changes carefully, as marked comparisons are not generally available and some amendments may be significant.
- Consumer credit: a consultation on the JFSC’s policy approach and the proposed code of practice for the new consumer credit regime is expected in Q4 2026.
AI guidance
- The JFSC’s Guidance on the use of AI in Jersey’s financial services sector was published in July.
- The guidance encourages responsible AI adoption and classifies use cases as low, medium or high risk within the existing regulatory framework.
- Many AI use cases may fall into the medium risk category, particularly where sensitive data is involved. Material use cases should be reflected in the business risk assessment and supported by appropriate data protection analysis and competent human oversight.
- Firms should establish contingency arrangements for AI dependent critical processes and assess whether other regimes, particularly the EU AI Act, impose a higher compliance standard.
- For more details, please refer to our update: JFSC publishes AI guidance for Jersey’s financial services sector.
Contact
Felicia de Laat
Stefan Chinniah
Benjamin Marshall
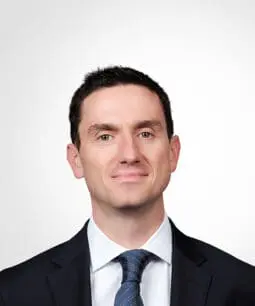
Mike Jones
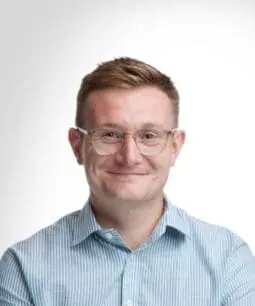
Tom Grogan
This update is only intended to give a summary and general overview of the subject matter. It is not intended to be comprehensive and does not constitute, and should not be taken to be, legal advice. If you would like legal advice or further information on any issue raised by this update, please get in touch with one of your usual contacts. You can find out more about us and access our legal and regulatory notices at mourant.com. © 2026 MOURANT ALL RIGHTS RESERVED

Consulting Services

Investment Funds

Regulatory and Governance
 News
1 October 2026
Mourant celebrates top rankings in Legal 500 UK 2027
 Update
30 September 2026
Guernsey FinReg Quarterly Update – July to September 2026
 Update
30 September 2026
Guernsey Accelerates its Digital Finance Proposition
 News
25 September 2026
Mourant celebrates 15 years in Asia
 Update
 Update
Sign up
Subscribe to keep up-to-date with the latest news, updates, legal guides and thought leadership articles.
Ready to take the next step? Let’s talk.
Send our team a message and we’ll be back in touch with you.